What Are the Most Common Budgeting Mistakes? (And How to Avoid Them)
Stay on track without the headache. Download our Free Monthly Budget Planner Excel Template and build a fail-proof financial routine!
Budgeting looks easy on paper: write down what you earn, list what you spend, and save the rest. But as anyone who has ever tried it knows, the real world has a habit of messing up the best-laid plans. It’s incredibly frustrating when you start the month with high hopes, only to be thrown off track by an unexpected bill, a math error, or a wave of burn-out.
Most people aren’t bad at budgeting; they’re just falling into some very common, hidden traps. If you want to know how to make a personal budget that actually works, you must first learn the classic pitfalls that cause most people to fail—and how you can bypass them.
1. Planning to the Last Penny (Over-Categorizing)
The most common way beginners set themselves up to fail is by creating too many tiny, hyperspecific categories. Having a separate budget for “Coffee”, “Office Snacks”, “Grocery Store Lunches”, and “Friday Dinners” is an administrative nightmare.
+-------------------------------------------------------------+
|                      BUDGETING MISTAKES                     |
+-----------------------------+-------------------------------+
|         PITFALL             |             FIX               |
|  Planning to the last penny | Simplify into broad buckets   |
|  Neglecting sinking funds   | Map irregular yearly costs    |
|  Skipping the "fun" fund    | Allow flexible guilty-spending|
+-----------------------------+-------------------------------+
- The Problem: It takes forever to track, makes logging a chore, and leads to guilt and over-complication when you miscalculate by a few cents.
- The Fix: Simplify. Combine those micro-budgets into one broad, easy-to-manage “Dining & Social” bucket. The simpler your system is, the longer you’ll use it.
2. Neglecting Sinking Funds (The Sneaky Bills)
Your monthly budget is only half the story. There are dozens of irregular, seasonal, or once-a-year expenses that can easily demolish your savings:
- Car registration & insurance
- Medical & dental co-pays
- Holiday and birthday gifts
- Back-to-school supplies
- Bi-annual utility adjustments
- The Problem: When these bills inevitably land, they feel like an “emergency” and force you to dip into your savings, disrupting your momentum.
- The Fix: Map out your known irregular costs over the next 12 months, divide by 12, and set aside a “sinking fund” contribution each month. This ensures you have the cash sitting waiting when the bill finally arrives.
3. Cutting Out All the Fun (Scarcity Mindset)
Going on a crash diet doesn’t work, and neither does a crash budget. If your budget doesn’t allow for any fun, leisure, or social activities, it’s only a matter of time before you throw in the towel out of frustration.
- The Problem: A completely restrictive “needs-only” budget feels punishing, and usually leads to a relapse of impulse spending.
- The Fix: Adopt a balanced system like the 50/30/20 budgeting rule. Always make room for some guilt-free “Wants.” A budget should be a tool that tells you how to spend your money, not that you can’t spend it.
4. Guessing Your Numbers
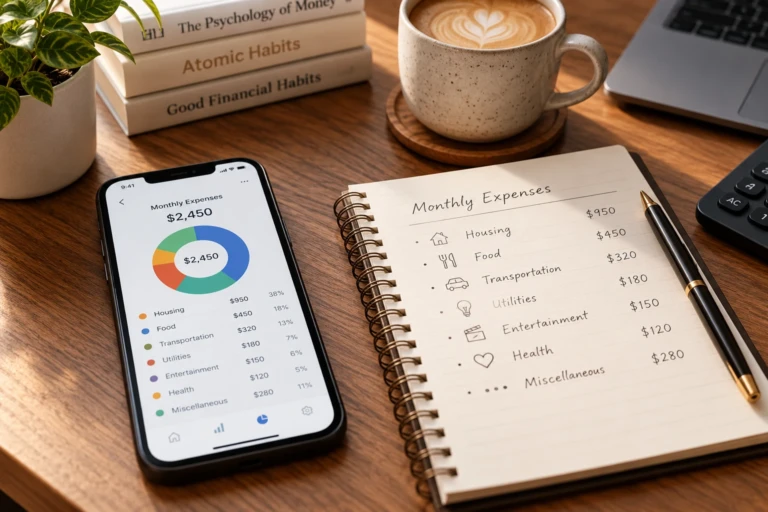
If you are guessing how much you spend based on your memory rather than your actual bank statements, your budget is likely inaccurate. Most people underestimate their actual variable spending (like food, shopping, and convenience) by as much as 30% to 50%!
- The Problem: If you budget $300 for groceries but consistently spend $550 without tracking, your entire system will constantly be short of cash.
- The Fix: Audit your past three months of actual bank statements to get a grounded, authentic average of what your expenses actually are. Take a few minutes to track monthly expenses accurately to build a realistic foundation.
Build a Resilient Budget
If you want a robust, pre-formulated tool that handles the hard work for you, download our Free Monthly Budget Planner Excel Template. Built to give you exact visibility over your funds without messy formulas, it ensures you stay realistic while avoiding critical mistakes.
Go Deeper:
Start from scratch and master the complete psychology of building a robust financial blueprint: How to Make a Personal Budget That Works.